If you rent out a flat, an apartment or a room for short stays, this is for you. Royal Decree-Law 29/2026 means that, from 1 December 2026, rentals of furnished homes for 30 nights or less will carry 10% VAT, even if you do not provide any hotel-type services. Until now, if there were no hotel-type services, these rentals were exempt, meaning they carried no VAT. Here is what you need to know:
What is changing?
Until 30 November
Exempt
No VAT, if you do not provide hotel-type services
From 1 December
10%
Stays of 30 nights or less by the same tenant, even without hotel-type services
Who is affected?
What matters is not whether the property is a holiday let or which platform you use, but how many nights the same tenant stays. So it affects:
On the other hand, these remain VAT-free (as long as there are no hotel-type services):
What if I already provide hotel-type services?
If during the stay you provide regular cleaning, change the sheets and towels regularly, offer breakfast or have a reception, the rental already carries 10% VAT today, whatever its length. This does not change. However, cleaning on arrival and departure, changing the linen between guests and maintenance are not considered hotel-type services. If this is your case and you are not charging VAT, talk to us as soon as possible.
How can you tell if your rental carries VAT?
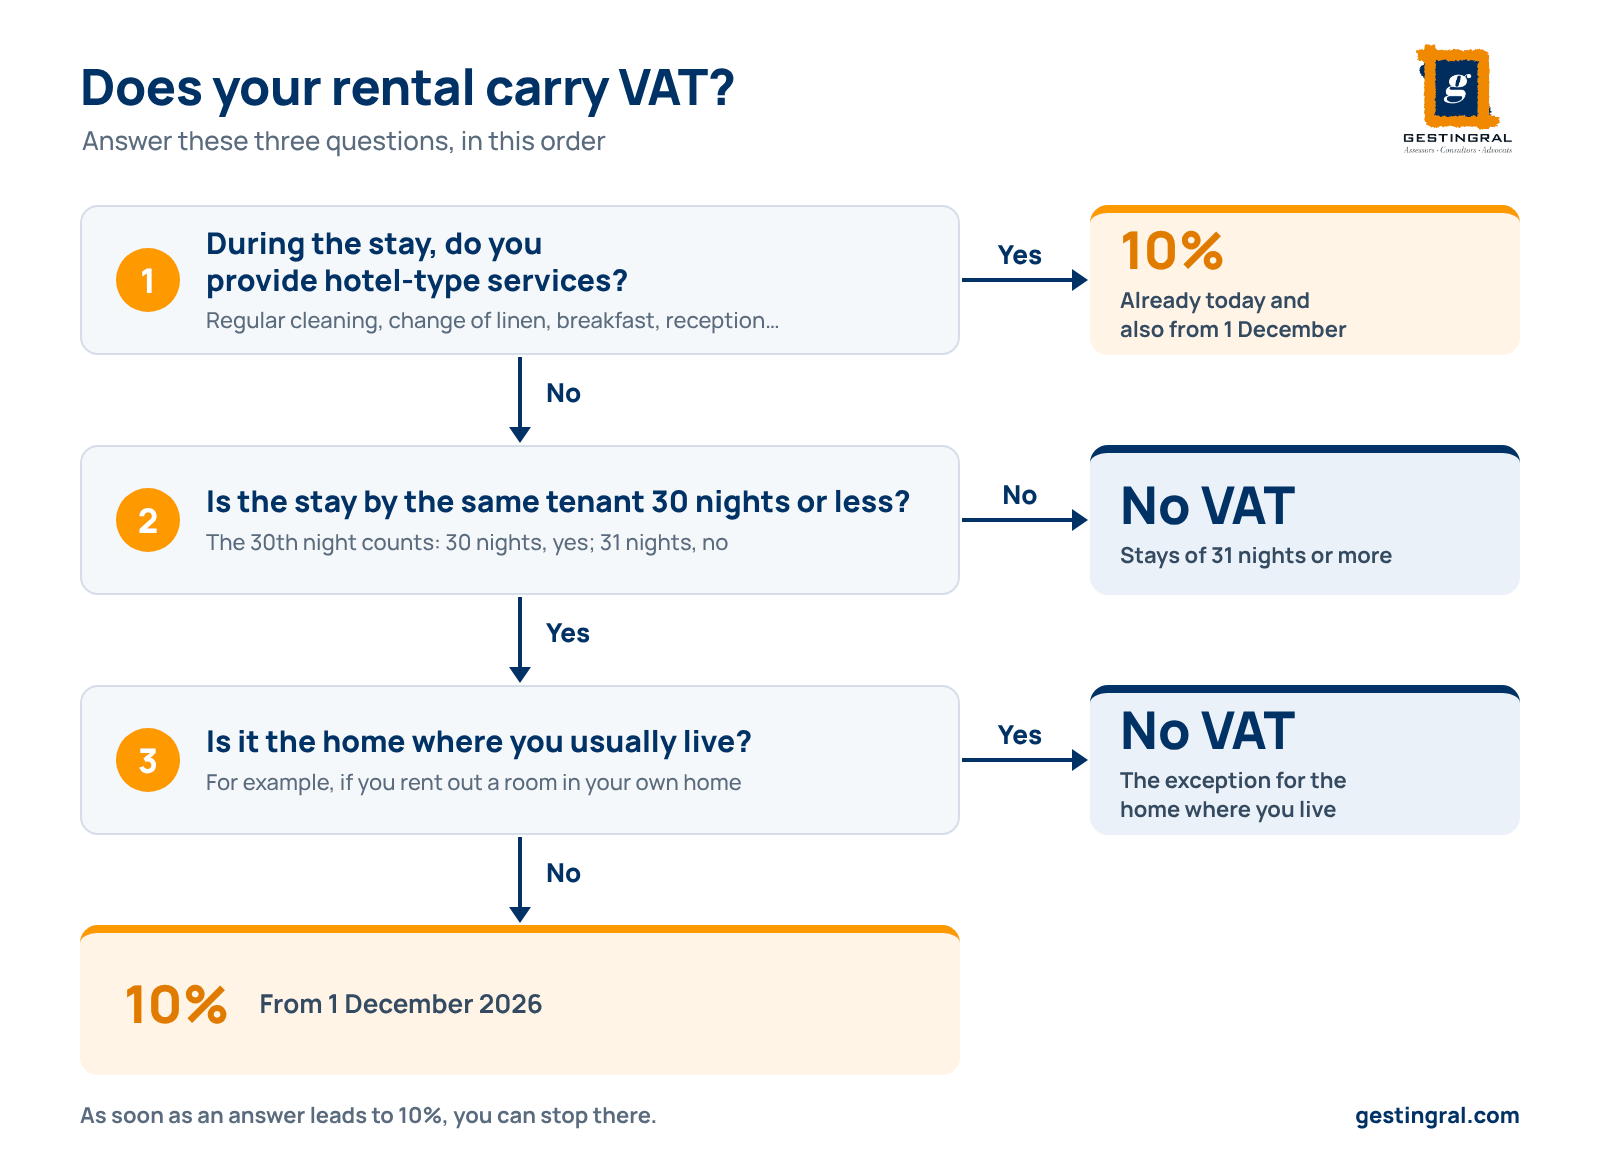
Ask yourself these three questions, in this order. As soon as an answer leads to 10%, you can stop there:
Some examples
| Case | Until 30/11/2026 | From 1/12/2026 |
|---|---|---|
| Holiday flat, 4 nights, no hotel-type services | No VAT | 10% |
| Exactly 30 nights, no hotel-type services | No VAT | 10% |
| 3 weeks to a student or a posted worker, no hotel-type services | No VAT | 10% |
| 31 nights or more (seasonal rental), no hotel-type services | No VAT | No VAT |
| A room in the home where you live, 2 weeks, no hotel-type services | No VAT | No VAT |
| Any stay with regular cleaning during the stay | 10% | 10% |
| Long-term rental where the tenant has their home | No VAT | No VAT |
Highlighted in orange: the cases that change from 1 December.
What will you need to do if your rental becomes subject to VAT?
For VAT purposes, you will be treated like a small business. In practice, you will need to:
If the property belongs to more than one person (for example, a couple or siblings), talk to us before registering: you need to decide carefully how the VAT will be declared.
And what about booking prices?
You will need to decide whether to raise your prices or absorb the VAT. For example, for a €480 booking:
- If you add VAT, the guest will pay €528 (€480 + €48 VAT).
- If you keep the price, only €436.36 of the €480 will be yours and €43.64 will be VAT.
And on your income tax return?
Nothing changes. Even though you are treated as a “business” for VAT purposes, on your personal income tax return (IRPF) the rental is still declared as before, as income from real estate, as long as you do not provide hotel-type services or employ someone full-time to manage it. This means you will not have to make quarterly income tax prepayments (Form 130). The only difference is that the VAT you charge is not your income and the VAT you deduct is not an expense. If you do not live in Spain, the same applies to non-resident income tax.
Our advice
Check each rental now with the three questions. If any stay from 1 December will carry VAT, let us know in good time so we can register you before the first stay, decide how you will adjust prices for new bookings and ask for all expense invoices in your name.
If you have any questions about how this change affects you, contact us and we will advise you.
